MEDICARE SERVICES
Medicare Supplement (Medigap)
Coverage that works alongside Original Medicare.
Medicare Supplement insurance, also called Medigap, can help pay some of the out-of-pocket costs that Original Medicare doesn’t cover. We’ll help you understand how Medigap works, compare available plans, and consider the coverage, costs and flexibility that matter to you.
MEDICARE SERVICES
- Turning 65 & New to Medicare
- Medicare Advantage
- Medicare Supplement
- Prescription Drug Coverage
- Annual Medicare Reviews
- Medicare & Medicaid
- Medicare Support & Advocacy
WHY MEDICARE SUPPLEMENT GUIDANCE?
- Understand how Medigap works
- Compare available plans
- Understand Plan G, Plan N & other options
- Review your potential out-of-pocket costs
- Understand enrollment timing
- Consider provider and travel needs
- Get support beyond enrollment
BEFORE CHOOSING A PLAN
- Your current Medicare coverage
- Your doctors and specialists
- Preferred hospitals
- Prescription medications
- Expected healthcare needs
- Potential out-of-pocket costs
- Travel needs
- Budget and financial priorities
Need Help Comparing Plans?
Medicare Supplement plans can help fill certain gaps in Original Medicare.
We’ll help you understand your options before you make a decision.
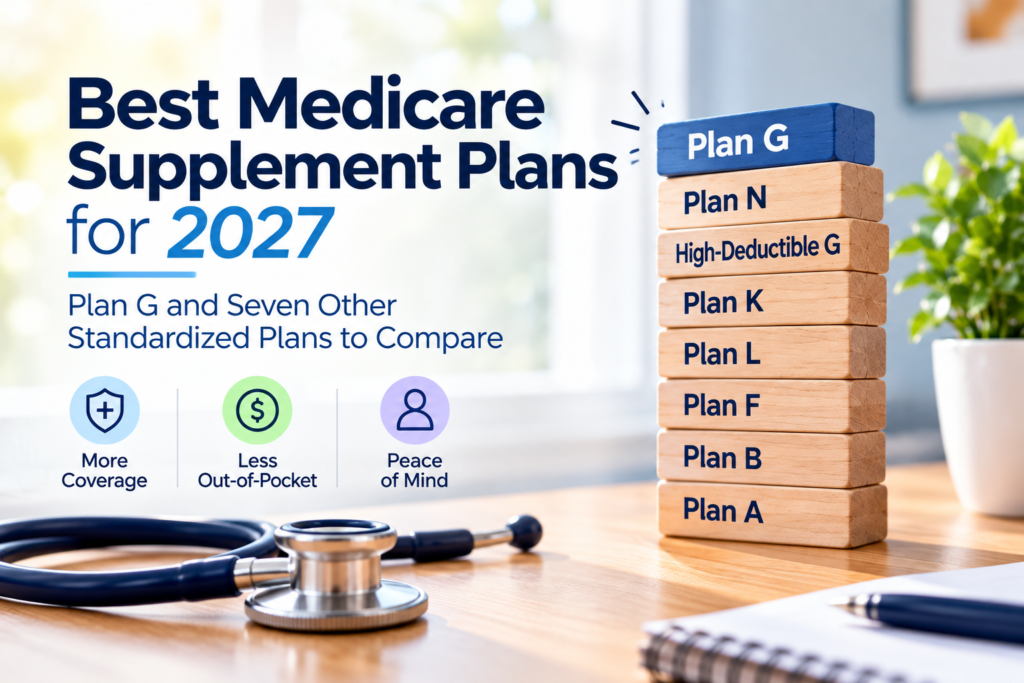
UNDERSTANDING MEDICARE SUPPLEMENT
What Is Medicare Supplement (Medigap)?
Medicare Supplement Insurance, commonly called Medigap, is additional insurance you can purchase from a private insurance company to help pay some of the healthcare costs that Original Medicare doesn’t fully cover.
Depending on the plan, Medigap can help with expenses such as coinsurance, copayments and deductibles associated with covered Original Medicare services.
Medigap works with Original Medicare, rather than replacing it. You remain enrolled in Medicare Part A and Part B, and Medicare continues to process your covered healthcare claims.
Important:
Medigap plans are standardized by letter, but premiums can vary between insurance companies. We’ll help you understand the differences between the available plans and compare costs based on your needs and budget.
HOW MEDIGAP WORKS?
How Medicare Supplement Works
Medigap works alongside Original Medicare to help cover certain costs that Medicare doesn’t fully pay.
You Have Original Medicare
You must generally have Medicare Part A and Part B before purchasing a Medigap policy.
You Choose a Medigap Plan
You select a standardized Medigap plan offered by a private insurance company in your area.
Medicare Pays First
When you receive Medicare-covered care, Original Medicare pays its share first.
Medigap May Pay Its Share
Depending on the plan you've selected, Medigap may help pay certain remaining covered costs.
You Keep Your Medicare Doctors
Because Medigap works with Original Medicare, you can generally see any doctor or healthcare provider who accepts Medicare.
MEDIGAP PLANS
Medigap Plans: Understanding the Letters
Medigap policies are standardized in most states and identified by letters. The benefits associated with the same letter are generally the same regardless of which insurance company sells the policy; the premium and other pricing can differ between companies.
WHAT SHOULD YOU COMPARE?
Choosing a Medigap Plan Is About More Than the Letter
A plan with a low premium may not necessarily be the best fit for someone’s doctors, prescriptions, network or expected healthcare needs.
Doctors & Hospitals
Are the providers you want to continue seeing included?
Prescription Coverage
Are your medications covered, and what will you pay?
Pharmacy
Is your preferred pharmacy in the plan's network?
Premium
What is the monthly premium for the plan?
Copays & Cost-Sharing
What might you pay when you receive care?
Maximum Out-of-Pocket
What is the plan's yearly limit for covered Medicare services?
Provider Network
What network rules apply to your care?
Travel
How does the plan handle care when you're away from home?
Additional Benefits
Which extra benefits are included, and are they useful to you?
MORE THAN AN ENROLLMENT
Don't Just Choose an Agent. Get an Advocate.
Choosing a Medicare plan is only part of the journey. At Pro Compare Medicare, we believe people deserve to understand what they're choosing and why they're choosing it. We're here to educate, compare and support you, not simply move you through an enrollment process.
PRESCRIPTION
Your Prescription Coverage Matters
The prescriptions you take can make a big difference when comparing Medicare Advantage plans. A plan may cover your medications, but your actual costs can vary based on the drug, its tier, the pharmacy you use and the plan’s coverage rules.
COSTS
What Can a Medicare Advantage Plan Cost?
The monthly premium is only one part of the picture. Medicare Advantage costs can include your Part B premium, plan premiums, deductibles, copayments, coinsurance and prescription costs. These amounts vary by plan.
ADDITIONAL BENEFITS
Look Beyond the Extras
Some Medicare Advantage plans offer benefits beyond Original Medicare, but additional benefits vary by plan and location. The important question isn’t simply whether a benefit is advertised, it’s whether it is useful to you.
ORIGINAL MEDICARE VS MEDICARE ADVANTAGE
Two Paths. Different Features.
Original Medicare ( Part A + Part B )
- Any doctor or hospital that accepts Medicare
- Separate Part D may be added
- Medigap may be added
- No yearly out-of-pocket limit under Original Medicare alone
MEDICARE ADVANTAGE ( Part C )
- Medicare-approved private plan
- Provider networks may apply
- Most plans include Part D
- Copayments and other cost-sharing vary
- Annual out-of-pocket limit applies for covered Medicare services
Neither approach is one-size-fits all.
Your doctors, prescriptions, healthcare needs, budget, travel and preferred providers all matter.
Is Medicare Advantage Worth Considering?
You may want to explore Medicare Advantage if you’re interested in:
- Receiving Part A and Part B benefits through one private plan
- A plan that includes prescription drug coverage
- Defined yearly out-of-pocket limits
- Certain additional benefits
- A plan with a provider network that works for your doctors and healthcare needs
But….
You should also consider whether the plan’s:
network → costs → prescriptions → rules → travel coverage
fit your situation.
HOW PRO COMPARE HELPS
Medicare Advantage Comparison, Without the Guesswork
Tell Us About You
We learn about your doctors, prescriptions, healthcare needs, budget and current coverage.
Compare Your Options
We review available Medicare Advantage plans and explain the differences in plain language.
Make Your Decision
You decide which option fits your needs.
We're Still Here
Our relationship doesn't end after enrollment. We're available for questions, coverage reviews and ongoing Medicare support.
Medicare Advantage Questions
Frequently Asked Questions
What is Medicare Advantage?
Medicare Advantage, also called Part C, is another way to receive your Medicare Part A and Part B benefits through a Medicare-approved private insurance company. Most plans include prescription drug coverage.
Do I have to pay my Part B premium if I join Medicare Advantage?
Yes. You generally continue paying your Part B premium while enrolled in a Medicare Advantage plan.
Are all Medicare Advantage plans the same?
No. Plans can differ in premiums, networks, costs, prescription coverage, rules and additional benefits.
Can I keep my doctor?
It depends on the plan. Check whether your doctors and other providers participate in the plan’s network.
Do Medicare Advantage plans include prescription drug coverage?
Most Medicare Advantage plans include Part D prescription drug coverage, but you should check the specific plan.
What are the different types of Medicare Advantage plans?
Common types include HMO, PPO, PFFS, SNP and MSA plans.
Do Medicare Advantage plans have an out-of-pocket limit?
Yes. Medicare Advantage plans have a yearly limit on what you pay for covered Medicare services. The specific limit varies by plan.